01 · Holambra: a Dutch colony that became Latin America's flower capital.
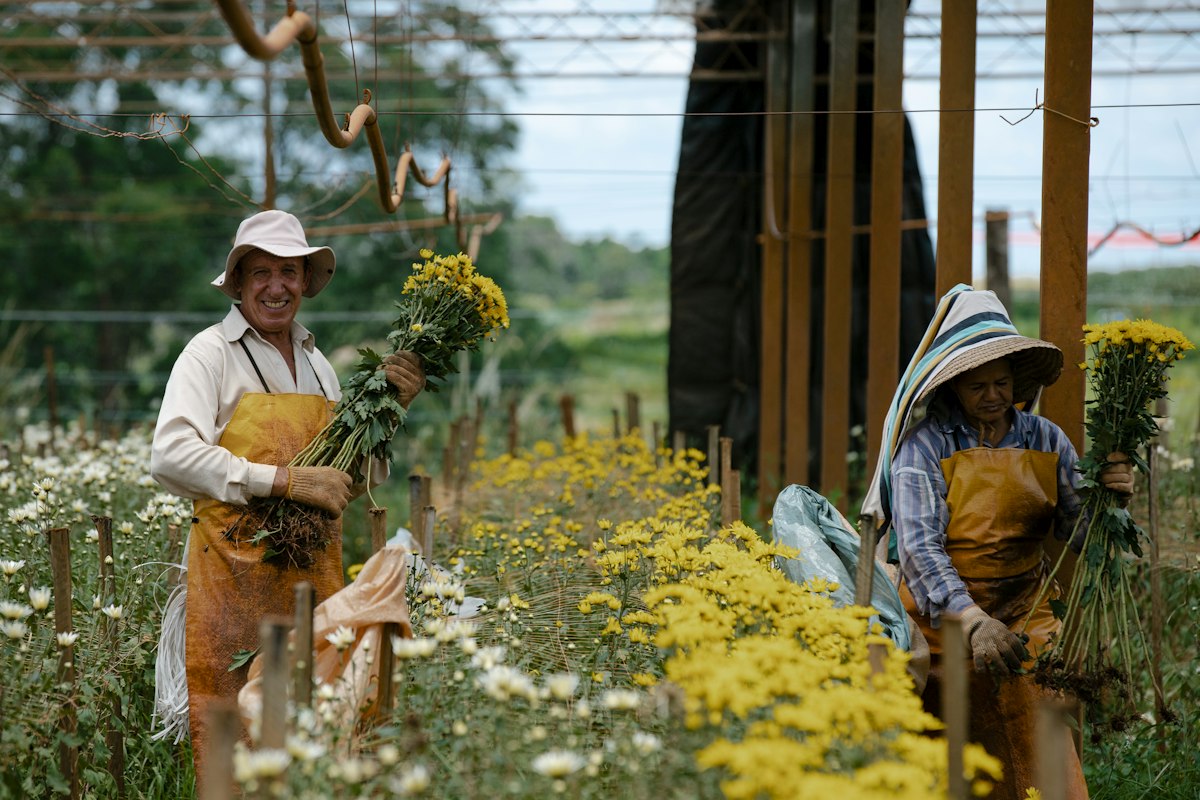
Holambra is a municipality of about 15,000 in the interior of São Paulo state, 130 km from São Paulo city. Founded by Dutch immigrants in 1948, the city and its surrounding municipalities — Santo Antônio de Posse, Jaguariúna, Artur Nogueira, Mogi Mirim — form a concentrated cluster of more than 400 flower and ornamental plant producers, two major cooperatives and a dense ecosystem of input suppliers, including substrate companies.[1]
The Cooperativa Veiling Holambra, based in Santo Antônio de Posse, is the fifth-largest flower auction in the world by volume, with 450+ member producers, more than 1,000 registered buyers, 7,000+ varieties, and about 45% of Brazil's flower commerce passing through its reverse auction system.[2] Cooperflora, the second cooperative, represents about 50 producers specialized in cut flowers, with 6,000+ m² of refrigerated storage.[3]
The Ceaflor wholesale market in Jaguariúna, with 228,000 m² and 946 boxes, functions as the "CEASA of flowers" — a convergence point for producers, distributors and retailers across Brazil.[4]
02 · Brazil's floriculture market: R$ 21 billion and growing.
| Metric | Value | Year | Source |
|---|---|---|---|
| National GDP (floriculture chain) | R$ 21.23 billion | 2024 | Ibraflor/CEPEA 2024 |
| Year-on-year growth | +9.95% | 2024 | Ibraflor 2024 |
| Number of producers | 8,300 | 2024 | Ibraflor 2024 |
| Area cultivated | 16,380 ha | 2024 | Ibraflor 2024 |
| São Paulo state share of national GDP | 40% (R$ 8.49 billion) | 2024 | Ibraflor 2024 |
| Direct employment | 264,874 workers | 2024 | Ibraflor 2024 |
| Holambra share of national production | ~40% | 2024 | Ibraflor / Portal de Holambra |
| Growth projection for 2025 | +9% | 2025 | Veiling Holambra |
Production breakdown. Flowers in pots (vasos): 58%. Ornamental plants: 24%. Cut flowers: 15%. Others: 3%. Post-pandemic flower consumption has become structural, not just seasonal: the largest cooperative in the cluster expects to sell 22 million flowers for Mother's Day alone.[5]
03 · The substrate market: R$ 517 million and 750,000 m³.
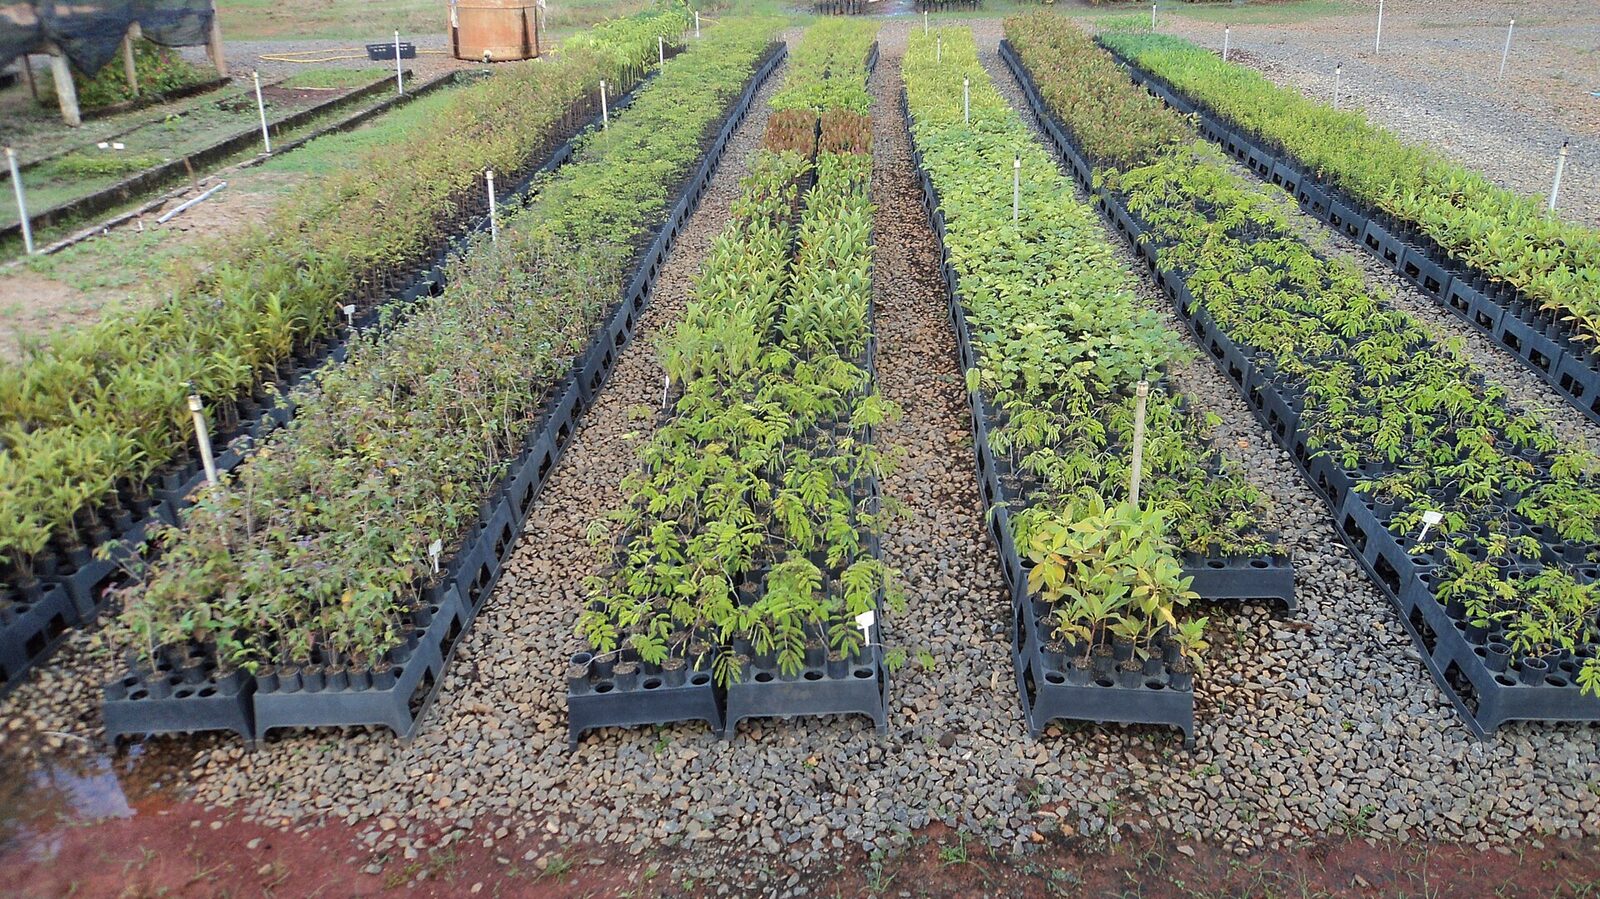
Brazil's substrate industry generated R$ 517.2 million in revenue in 2025, up 22.8% from 2024, according to the national trade association. Volume commercialized in 2024 was approximately 750,000 m³. The Sudeste region (which includes Holambra and greater São Paulo) accounts for 53.5% of all substrate sold nationally, followed by the Sul at 23.2% and the Nordeste at 12.7%.[6]
By end use, the industry divides the market: forestry seedlings ~21%, vegetables 20%, fruit 16%, coffee/citrus/sugarcane 16%, flowers and ornamentals 15%, tobacco 12%.[6]
04 · Key segments in the Holambra cluster: who buys substrate.
The Holambra cluster's substrate buyers fall into four categories, each with different volumes, formats and quality requirements:
1. Large greenhouse operations (>5 ha) — buy substrate by the truckload (carreta), use 50–200+ m³/yr. These are the anchor buyers for any substrate supplier, and they negotiate directly on specs and price.
2. Medium pot-flower producers (1–5 ha) — buy by the pallet, 20–50 m³/yr. They source through the cooperatives or directly from input suppliers based in the cluster.
3. Small specialty growers (<1 ha, orchids, bromeliads, succulents) — buy bags, 5–20 m³/yr. Orchid growers are a premium segment: they specify chips mixed with fiber, and they pay more per cubic metre.
4. Nurseries (viveiros) — seedling production, high substrate turnover. Tubete-based systems consume fine coir pith at scale; a single nursery producing a million seedlings a year can use 200+ m³ of substrate.
Substrate specs demanded by segment
| Parameter | Ornamentals (pots) | Orchids | Cut flowers | Seedlings |
|---|---|---|---|---|
| EC (1:5) | < 1.0; < 0.7 for sensitive | < 0.5 (buffered preferred) | < 1.0 | < 1.5 |
| pH | 5.5–6.5 | 5.5–6.0 | 5.5–6.5 | 5.0–6.5 |
| Particle size | Fine to medium (<4 mm) | Chips 10–20 mm + fiber | Fine to medium | Fine (<4 mm) for tubetes |
| Format | Saco 100L, Big Bag 1,000L | Saco 5–50L | Saco 100L, bulk | Saco 50–100L |
Carve supplies natural, washed and buffered coir pith and coir fiber for all four segments. The three grades differ by EC: natural (raw, EC varies by husk origin), washed (< 1.0, typically < 0.7 mS/cm), and buffered (< 0.5, calcium-nitrate treated to displace exchange-bound potassium and sodium).
05 · Logistics: Paraipaba to Holambra, 2,800 km.
| Route | Distance | Transit |
|---|---|---|
| Paraipaba, CE → Holambra, SP | ~2,800–3,100 km | 3–4 days |
| São Paulo, SP → Holambra, SP | ~126 km | Same day (1h30) |
Freight cost. The CE→SP corridor runs approximately R$ 400–600/t depending on load size, season and truck availability. Two strategies reduce the effective cost: buyer collects (FOB origin), or backhaul arbitrage — trucks returning empty from SP to CE can be negotiated at 40–60% of full-load rates.[8]
How substrate arrives today. Regional processors ship from Pará (~3,000 km), Bahia (~1,800 km), or import compressed blocks through Santos/Paranaguá ports, then truck 250–350 km to Holambra. Substrate formulators based in the cluster buy raw coir as an input and blend it with peat, perlite, vermiculite or pine bark before selling the finished product to growers.[9]
06 · Pricing: domestic market references.
| Channel | Product | Price | R$/m³ | Source |
|---|---|---|---|---|
| Bulk B2B (unwashed) | Pó fino, 100L bags | R$ 18–22/saco | R$ 180–220/m³ | MF Rural, pipeline data |
| Blender input | Raw pó, CE origin | R$ 26–27/saco 100L | R$ 260–270/m³ | Transaction data |
| Washed B2B | EC < 0.7, Big Bag | R$ 318/m³ | R$ 318/m³ | Pipeline data |
| E-commerce retail | Branded substrate, 107L | R$ 299.99/107L | ~R$ 2,800/m³ | E-commerce listing |
| Imported blocks | Indian/Sri Lankan, landed | — | R$ 280–330/m³ | Pipeline intel |
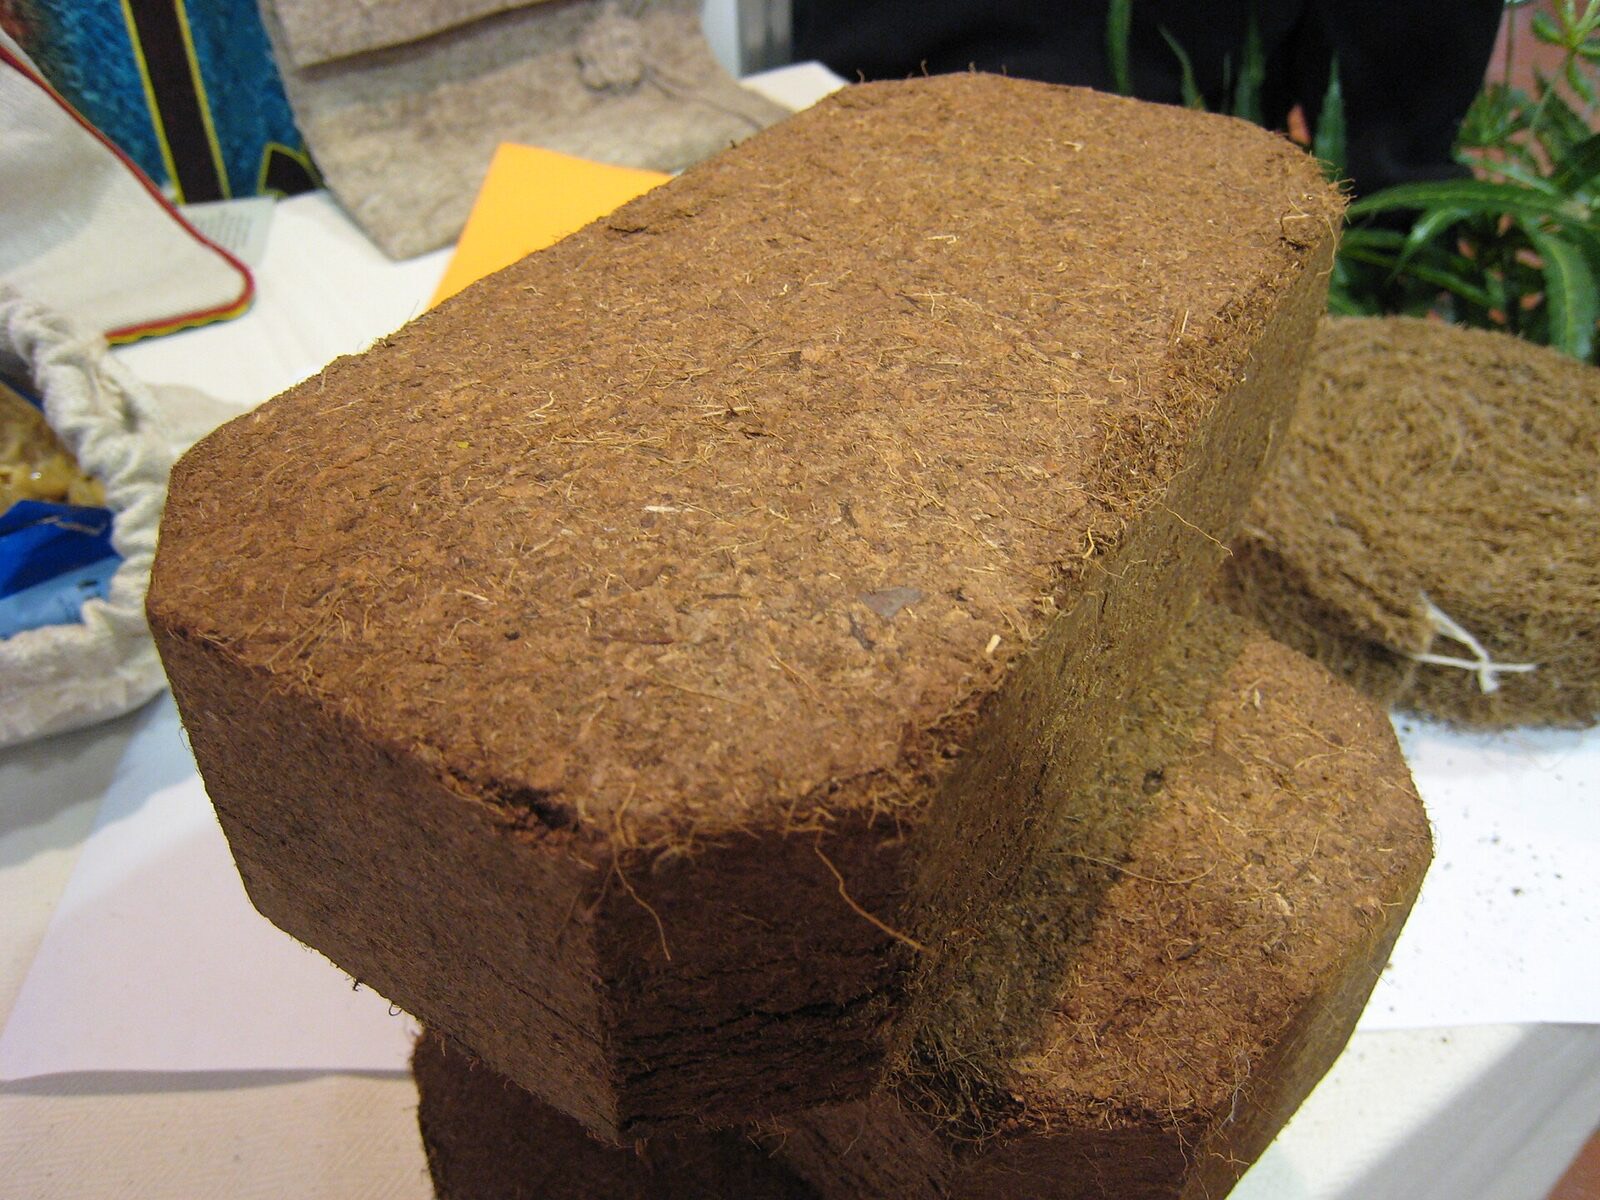
The blender markup is 3–4× from input to wholesale, and roughly 10× from input to retail. No Brazilian processor currently manufactures the 5 kg compressed coco peat block or buffered (calcium-nitrate treated) pith that the strawberry and blueberry sectors import from India.[10]
07 · Growth drivers: peat replacement, orchids and greenhouses.
Peat replacement
EU legislation is driving global coir reputation as the primary renewable alternative to peat. Some substrate formulators in the Holambra cluster already import peat from Estonia, which will become more expensive as European peat-reduction targets tighten. The Dutch covenant commits professional growing media to 50% renewable content by 2030; any formulator exporting to the EU or supplying multinational growers will face the same pressure domestically.[11]
Orchid boom
An estimated 7.8 million orchid pots were produced in Brazil in 2024, up roughly 20% year on year. Orchids require a specific substrate mix — chips (10–20 mm) combined with coir fiber and pine bark — and orchid growers pay a premium for low-EC, well-graded material. The orchid segment is the highest-value per-cubic-metre buyer of coir in the Holambra cluster.[12]
Protected cultivation
Brazil's commercial greenhouse market is projected to reach US$ 471 million by 2029 (CAGR 4.90%). The Holambra cluster has 106+ hectares of greenhouses, and each new greenhouse installation increases substrate demand because soilless systems replace soil beds with pots, bags or slabs that require growing media.[13]
Semi-hydroponic fruit
Strawberry production on substrate has reached approximately 45% of the national crop; hydroponic tomato, while still at about 3%, is growing at more than 15% per year. Both crops prefer washed coir with EC below 1.0 mS/cm, and the strawberry plateau of Minas Gerais — within 500 km of Holambra — is a significant and growing consumer of coir slabs and grow bags.[14]
08 · Frequently asked questions.
What is Holambra and why does it matter for coir?
Holambra is a municipality in São Paulo state founded by Dutch immigrants in 1948. It is the center of Brazil's R$ 21 billion floriculture industry, with 400+ producers, two cooperatives and the fifth-largest flower auction in the world. The cluster consumes an estimated 9,000 tonnes of coir substrate per year.
What substrate specs do Holambra producers require?
Most ornamental producers prefer coir pith with EC below 1.0 mS/cm (1:5 extract), pH 5.5–6.5, particle size below 4 mm and moisture below 20%. Orchid growers use chips (10–20 mm) mixed with fiber. Large greenhouse operations buy by the truckload in 100L bags or 1,000L big bags.
How far is Holambra from coir production in Ceará?
About 2,800–3,100 km by truck, 3–4 days transit time. São Paulo city to Holambra is 126 km (1h30). Backhaul trucks returning from SP to the Northeast can reduce freight costs by 40–60%.
What is the Hortitec trade show?
Hortitec is the largest horticulture expo in Latin America, held annually in June at Holambra. In 2025 it drew 520 exhibitors and 32,000 visitors, with R$ 600 million in projected business. It is the principal event for reaching Holambra substrate buyers.[17]
MARKET INTELLIGENCE BY REGION
Coir markets we cover
Sourced market data and import guides for the destinations we serve from Pecém, Brazil.
For the worldwide picture, see our Global Coir Market overview.
09 · Sources.
- Masterplanti / Portal de Holambra — Holambra cluster data, 400+ producers, Dutch-colony history and surrounding municipalities.
- mundocoop.com.br — Veiling Holambra, cooperative profile: 450+ member producers, 1,000+ buyers, 7,000+ varieties, ~45% of Brazil's flower commerce.
- Cooperflora — cooperativa dos floricultores, ~50 producers, 6,000+ m² refrigerated storage.
- Ceaflor — centro de comercialização, Jaguariúna, 228,000 m², 946 boxes.
- Exame / Veiling Holambra — Mother's Day 2025 flower volume projection (22 million flowers).
- ABISOLO, Anuário 2025/2026 — substrate market data: R$ 517.2 million revenue 2025 (+22.8%), 750,000 m³ volume 2024, regional breakdown (Sudeste 53.5%, Sul 23.2%, Nordeste 12.7%), end-use segmentation.
- Nordic peat harvest shortfall, industry reporting 2025 — Finland and Sweden harvest at 15–25% of plan; HortiDaily / FloralDaily; ABISOLO on price-driven revenue growth.
- FreteBras / general freight references, CE→SP corridor — R$ 400–600/t; backhaul arbitrage 40–60% discount.
- Industry logistics reporting, Brazil — substrate supply routes from Pará, Bahia and import through Santos/Paranaguá.
- Carve market research, 2026 — domestic processing gaps (no 5 kg block, no buffered pith manufactured in Brazil); blender markup multiples.
- Industry reporting — peat imports from Estonia; EU peat-reduction covenant impact on Brazilian formulators.
- Carve internal segment estimates — orchid production (~7.8 million pots in 2024, +20% YoY), premium substrate mix requirements.
- Plataforma Hidroponia / FAEMG — Brazil commercial greenhouse market projected to reach US$ 471 million by 2029 (CAGR 4.90%); Holambra 106+ ha greenhouses.
- IBGE / Embrapa — semi-hydroponic fruit data: strawberry ~45% on substrate nationally, hydroponic tomato ~3% growing >15%/yr.
- Ibraflor/CEPEA 2024 — floriculture GDP: R$ 21.23 billion, +9.95% YoY, 8,300 producers, 16,380 ha, 264,874 direct jobs; São Paulo 40% share (R$ 8.49 billion).
- IBGE, Produção Agrícola Municipal 2024 — coconut production, Paraipaba: 155,899 t, second-largest producing municipality in Brazil.
- Agrolink / Hortitec 2025 — trade show data: 520 exhibitors, 32,000 visitors, R$ 600 million in projected business.
- ABISOLO / Forbes Agro — substrate market overview, R$ 421 million in 2024 volume value, growth trajectory.